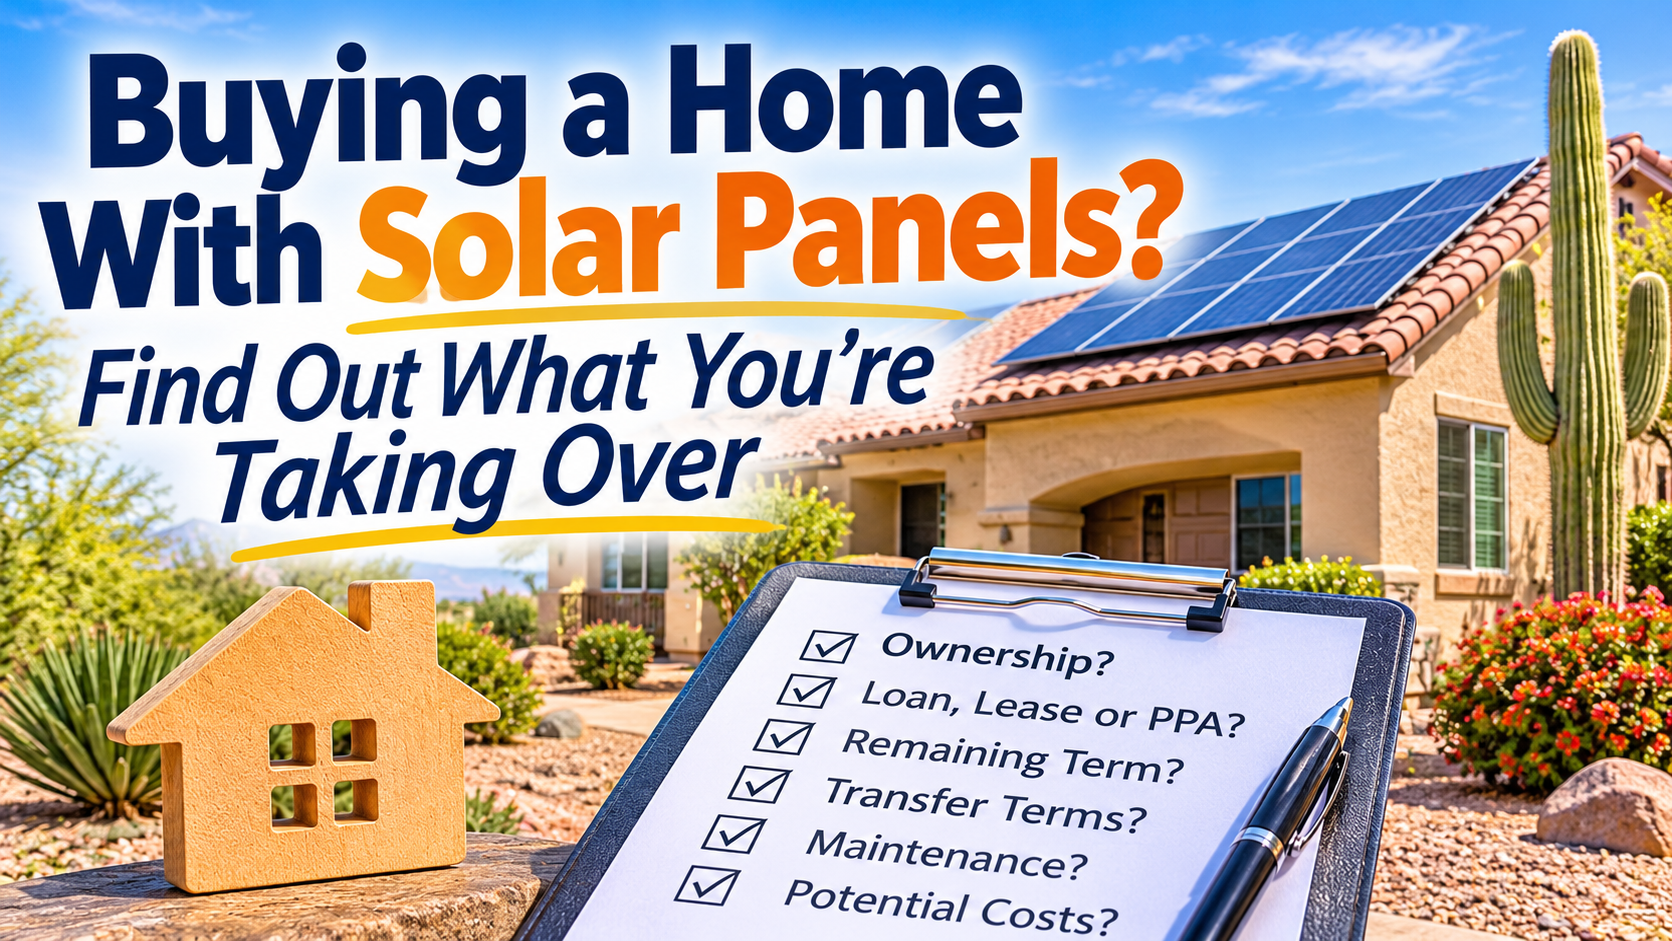
Solar panels can look like a selling point, but they can also complicate a real estate transaction. The system might be paid off, or it might come with a loan, lease, or long-term power purchase agreement, and the paperwork, the company, or both can be hard to pin down. Before you make an offer, find out exactly what you would be taking on.
You May Be Trading One Utility Bill for a 20-Year Obligation
Solar doesn’t always eliminate your electric bill. Depending on the system and the utility’s rate structure, you may still owe the utility for electricity, service charges, or power you need when the system isn’t producing enough. You may also have a separate payment to a solar company or lender. A solar loan, lease, or power purchase agreement (PPA, a contract to buy the power the system produces) can run for years, sometimes 20 or more.
That commitment deserves a close look. You might not own the system, control the agreement, or be able to end it when you sell. And if you move in five years, the obligation doesn’t disappear on its own. It may need to be paid off, transferred to the buyer, or handled under the contract’s terms. A buyer may not want it, may not qualify to take it over, or may walk away.
First, Find Out Who Owns the Solar System
Solar arrangements generally fall into a few categories, and the differences matter:
- Owned outright: The seller paid for the system. There may be nothing to assume, but you still need to verify ownership, equipment condition, warranties, and any recorded interests connected to the system.
- Solar loan: The homeowner owns the system, but a loan is still outstanding. Find the balance and payment terms, and confirm whether a lien (a legal claim against the property) or other security interest affects the house or the equipment. Determine what must happen to the loan when the home sells.
- Lease: A solar company owns the system, and the homeowner pays under a lease. Find out whether the lease can be transferred, what approval is required, and what the buyer would take on.
- Power purchase agreement: The homeowner buys the power the system generates under a separate contract. Understand the rate, payment terms, transfer requirements, and remaining term.
Don’t rely on the seller’s description or a listing that says the home has “owned solar.” Ask for the actual documents and verify the arrangement before you commit.
Check the Company and the Paperwork, Even If the System Is Paid Off
The business behind the equipment matters. The installer may not be the company that owns the system, services it, administers the agreement, or handles transfers. Companies can close, change names, sell their customer accounts, or pass contracts to another business. The original salesperson may be gone, and the company now managing the contract may have different procedures, contacts, or limited records.
Even when the original company is still operating, a real estate closing runs on deadlines, and a solar company may move on its own schedule. A payoff statement, transfer approval, corrected paperwork, or lien release can take longer than expected while the seller, buyer, lender, and title company wait. That delay is how a manageable arrangement can end up stalling a sale.
Paying off the system removes some risk but not all of it. You still need to confirm the seller owns the equipment and that any lien was released and recorded when required. Ask about the system’s age, performance, maintenance history, and known problems. Inverters, wiring, and monitoring equipment can need attention, not just the panels. Find out who installed the system, who services it now, and whether warranties transfer to you. Confirm who is responsible for honoring a warranty and how service requests are handled, rather than assuming the paperwork is enough.
Finally, check the roof. If it needs replacing, the panels may have to be removed and reinstalled. Find out who arranges that work, what it could cost, and whether the applicable agreements address removal and reinstallation.
Do the Numbers, and Think About Your Next Buyer
Don’t take the seller’s word that the system saves money. Ask for recent utility bills and production records. Review the loan, lease, or PPA, including the payment, remaining term, rate increases, and transfer requirements. Compare those costs with what you would otherwise pay for electricity. Actual savings depend on how much power the system produces, how much your household uses, when you use it, and how the utility credits excess production, so the seller’s experience may not match yours. Look at the total cost over the life of the agreement, not just the monthly payment. If the numbers don’t add up, the system may be an expense rather than a benefit.
You may be comfortable with the arrangement today, but your next buyer might not be. A buyer may be reluctant to take over a solar loan, lease, or PPA, may have to qualify for a transfer, or may have to accept terms they didn’t negotiate. If the buyer refuses, you may need a permitted payoff or another solution under the agreement. Those requirements can narrow your buyer pool and complicate negotiations, and a buyer who likes the house may still walk away over the solar contract. If the company has changed hands or disappeared by then, resolving those questions will be harder.
Make Solar Part of Your Due Diligence
Start the solar paperwork early, not in the last days before closing, so you have time to resolve problems. Before you commit, confirm:
- Who owns the panels and related equipment
- Whether a loan, lease, PPA, lien, or other obligation remains
- What documents govern the system, and whether the seller has complete copies
- Which company currently administers the agreement, services the system, and handles transfers or payoffs
- Whether a transfer requires approval, a credit check, fees, or other conditions
- The actual payments, remaining term, utility costs, and expected savings
- Whether warranties transfer and who will honor them
- Whether the roof, equipment, or paperwork needs to be resolved before closing
If a payoff or lien release is required, find out who must provide it and what the title company needs. Sometimes an agreement must be transferred, confirm the requirements and timing directly with the company responsible, and don’t assume a request is finished because someone says it’s being handled. If answers are unclear, documents are missing, or the company isn’t cooperating, treat that as a real transaction risk. Discuss it with your Realtor®, lender, and title company, and consult an attorney when the contract needs legal review.
Solar can be a good investment for some homeowners, but buying a home with solar means evaluating the equipment, the financial arrangement, the companies behind it, and the obligations that may remain when you sell. Get the answers before you buy. A little skepticism now can keep you from inheriting a problem that takes months, or substantial money, to resolve.